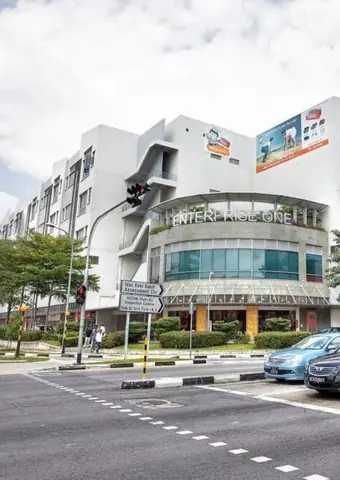
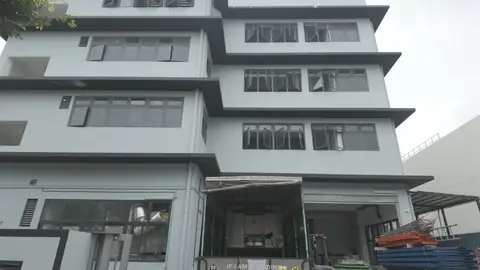
Freehold5 min walk to Macpherson MRT (DTL + CCL)4.8m ceiling · 12.5 kN/sqm floors
District 14 · Macpherson · Freehold B1 industrial
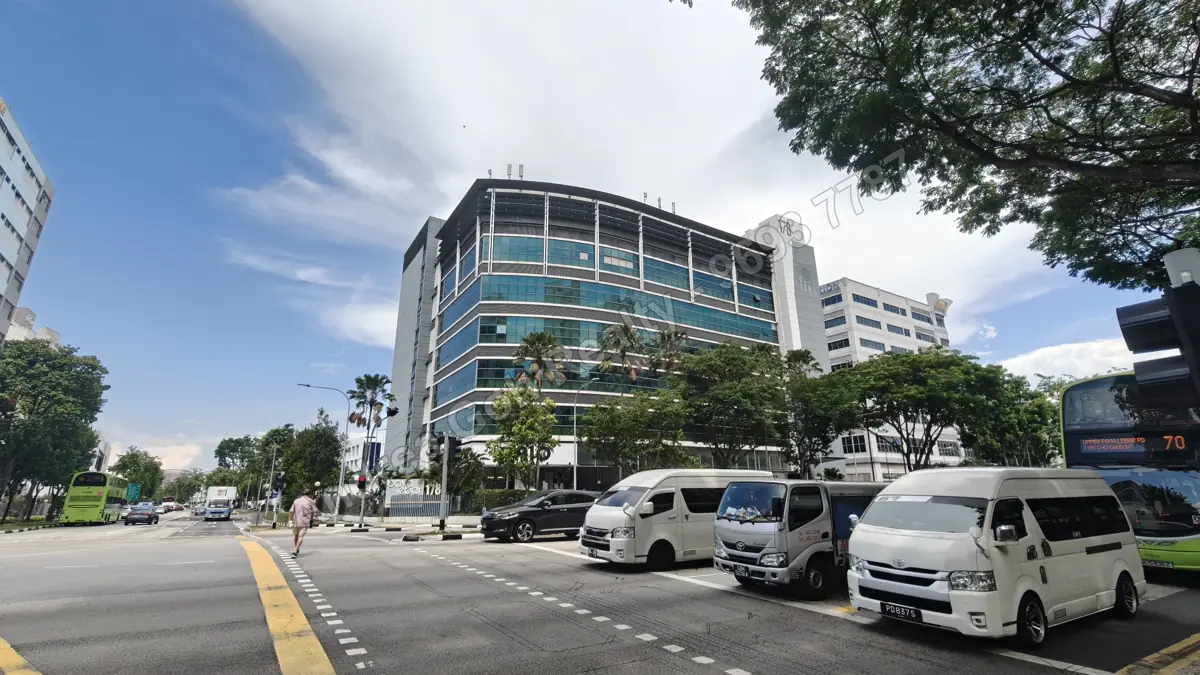
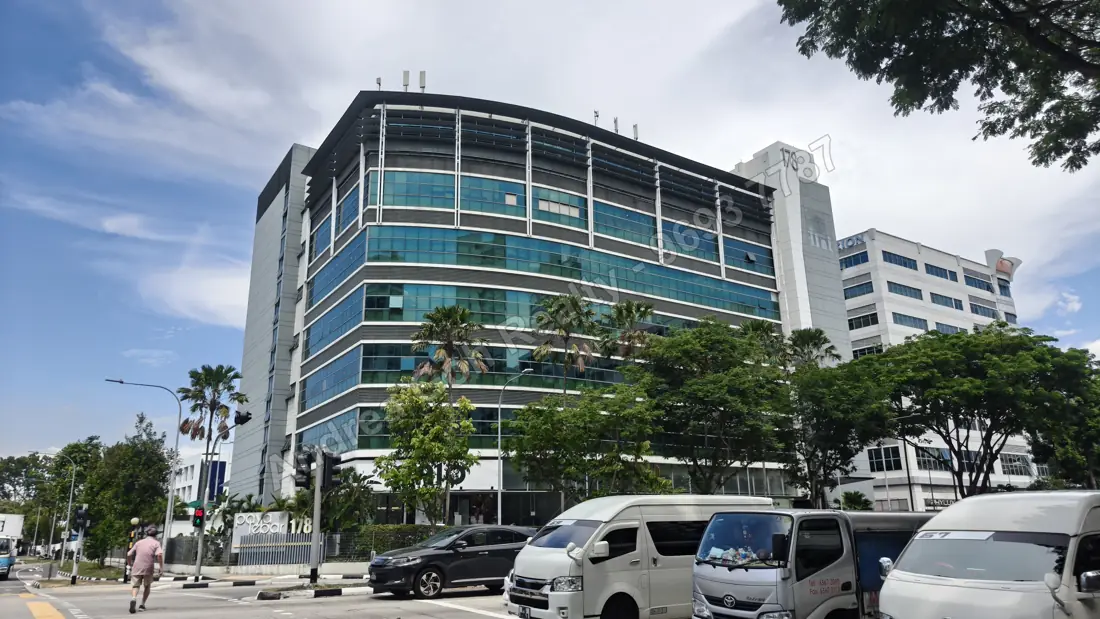
Paya Lebar 178
Freehold B1 office/warehouse on Level 3 — an adjoining corner pair combining to 3,089 sqft, plus a separate tenanted unit. Five minutes' walk to a two-line MRT interchange.
From S$2,378,299 per unitS$1,700 psf · S$7,629,599 for all three (excl GST)
Tenure = how long you legally own the property (e.g. Freehold, or a 99-year lease). TOP = Temporary Occupation Permit, the date the building is legally ready to move into.
The price, in context
Asking S$1,700 psf. Recent sales nearby: S$3 to S$1,507.
This unit S$1,700
S$3lowestS$1,350median of 6S$1,507highest
How to read this. Each small dot is one recent sale nearby, plotted by price per square foot (6 sales). The gold dot is this unit's asking price per square foot. The tick marks the median, so half the sales sold for more and half for less. A dot to the left of gold sold for less per square foot. It compares price per square foot only: it does not account for floor, view, condition or renovation, and it is not a valuation.
Actual caveats near the subject, median S$1,350 psf. See each sale. Source and date are with the table below.
Vacantadjoins the next unit; the pair combines to 3,089 sqft
Next to corner · L3
1,399 sqft
S$2,378,299
S$1,700 psf
S$475/mo (S$1,425.60/qtr)
S$3,780/yr
Owner-occupiedadjoins the corner unit
Tenanted unit · L3
1,399 sqft
S$2,378,299
S$1,700 psf
S$475/mo (S$1,425.60/qtr)
S$3,780/yr
Tenanted to Aug 2027 at S$4,617/mostandalone, not adjoiningNet ≈ S$3,827/mo after MCST + tax (17% of rent) · ~1.9% net at asking
All three
4,488 sqft
S$7,629,599
S$1,700 psf
S$1,526/mo (S$4,579.20/qtr)
S$12,150/yr
Buy one, the corner pair, or all three
The three units on offer, individually priced (a fourth unit in this run sold in Jul 2026). Unit numbers withheld. The corner unit and its neighbour adjoin and can be combined into one 3,089 sqft footprint (in my opinion, and subject to approval from the authorities and the MCST); the standalone unit is separate. Prices exclude GST. MCST includes the sinking fund, quarterly fee shown per month, before GST, rates from 1 Jul 2025; property tax is the current annual figure per the owner's fact sheet (IRAS revises Annual Value yearly).
Net = stated rent less MCST and property tax, before GST, loan, fees and vacancy. Yield basis (CEA): gross yield = annual rent as stated above (passing or projected, per the stated basis) ÷ the stated asking price; net yield is after property tax (a flat 10% of Annual Value), MCST/service charge and outgoings. These are historical/indicative, not a forecast or a guarantee of return — verify the tenancy and the IRAS Annual Value independently before relying on them.
Cash flow: full cash or with a loan
Illustration only, not a quote or a forecast. Default rate = 3-month SORA 1.266% (MAS, 23 Oct 2026) plus an assumed 1.5% bank margin; your bank decides. Repayment includes principal. Cash in = price less loan, before stamp duty, GST and legal fees.
Why the return looks modest: in my view, freehold usually costs more than a comparable leasehold unit, so the same rent gives a lower yield. You are paying for a title that does not run down. Judge it on the monthly cash flow you can hold, not the yield alone.
Income & outgoings
What it earns — and what it costs to hold
Standalone unit — passing rent
S$4,617 / mo
Lease renewed to
Aug 2027
Annualised
S$55,400 / yr
Gross yield on S$2,378,299
~2.3%
Net after MCST + taxⓥ
~1.9%
Corner pair
Vacant / owner-occupied — available
Building rent benchmark (JTC)
median S$3.05 psf/mo, middle half S$2.40–3.07 (2025Q2)
Corner pair if let at the JTC medianⓥ
≈ S$9,400/mo · ≈ 2.2% gross at asking (indicative, not an offer)
Yield at your price
2.33% gross at asking (S$2,378,299)
At your price: 2.33% gross (S$55,400 a year ÷ your price, before costs)
Only the standalone unit is tenanted; the corner pair is available for occupation. The tenant renewed at S$3.30 psf, which is market validation of that rate rather than an asking. Commercial property tax is a flat 10% of Annual Value — the current assessment implies an AV below the passing rent, so budget for an upward revision.
Yield basis (CEA): gross yield = annual rent as stated above (passing or projected, per the stated basis) ÷ the stated asking price; net yield is after property tax (a flat 10% of Annual Value), MCST/service charge and outgoings. These are historical/indicative, not a forecast or a guarantee of return — verify the tenancy and the IRAS Annual Value independently before relying on them.
What makes it rare
Why this one
✓Freehold, in a market that stopped making it
New JTC industrial land is issued on 30-year tenures, so the freehold pool cannot grow. In Q1 2026 the average freehold industrial asset transacted at S$876 psf against S$569 for 60-year and S$353 for 30-year leasehold — and freehold was the only tenure band that rose while 30-year fell. (Savills)
✓An adjoining corner pair, in one ownership
The corner unit and its neighbour combine into a single 3,089 sqft footprint — you lay out one operation instead of splitting it across levels. A fourth unit in this run has already sold; the pair is what remains.
✓4.8m ceiling, 12.5 kN/sqm floors, six dock-leveller bays
Racking, a mezzanine and heavy plant fit without redesign. Containers unload direct at six 40ft bays with dock levellers, and two 4,000kg cargo lifts take loaded pallets up without breaking them down.
✓Not every alternative use is closed off
URA lists childcare, an industrial canteen and general industrial use as assessable at this address — a Change of Use application it will consider, rather than a flat no. With roughly 42,059 households in the Geylang planning area behind it, that matters most for a childcare operator. Approval is never guaranteed, so treat it as optionality, not a plan.
Approved use · by level
What each level can do — exactly
Level
Approved now
By change-of-use application
Not permitted
Level 3all units offered
Light Industrial Use (after NEA clearance)Ancillary office while industrial stays above 60%
Childcare centreIndustrial canteenGeneral industrial useOther uses (case by case)
Approved now By URA application (not guaranteed) Not permitted
URA SPACE per-unit check, 20 Jul 2026 (corner unit; Andrea confirms the same profile applies to all units offered). Read the middle column as an OPEN DOOR, not a refusal: URA asks for a Change of Use application it will assess, with landowner and (where relevant) NEA/LTA/PUB/SCDF clearances first — approval is not guaranteed, but these uses are not barred the way the right-hand column is. One carve-out to know: for multi-user industrial developments URA will only consider a new workers' dormitory in a SEPARATE BUILDING within the site, so it is not realistically available to a strata unit here. Approved use is granted PER UNIT — re-run URA SPACE on your specific unit and intended trade before committing.
Gallery
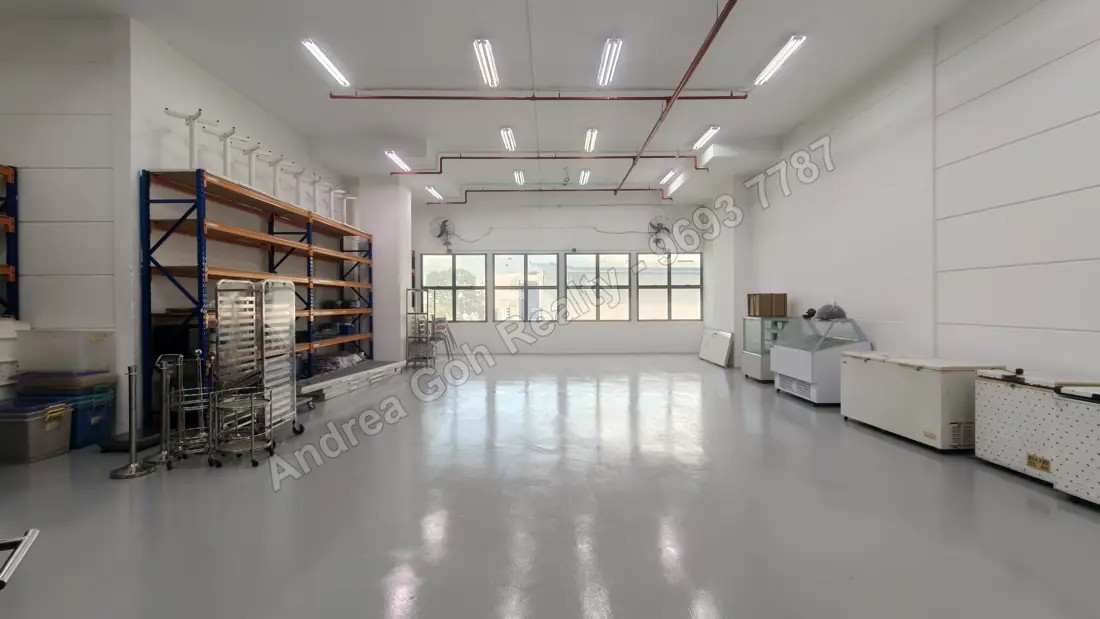
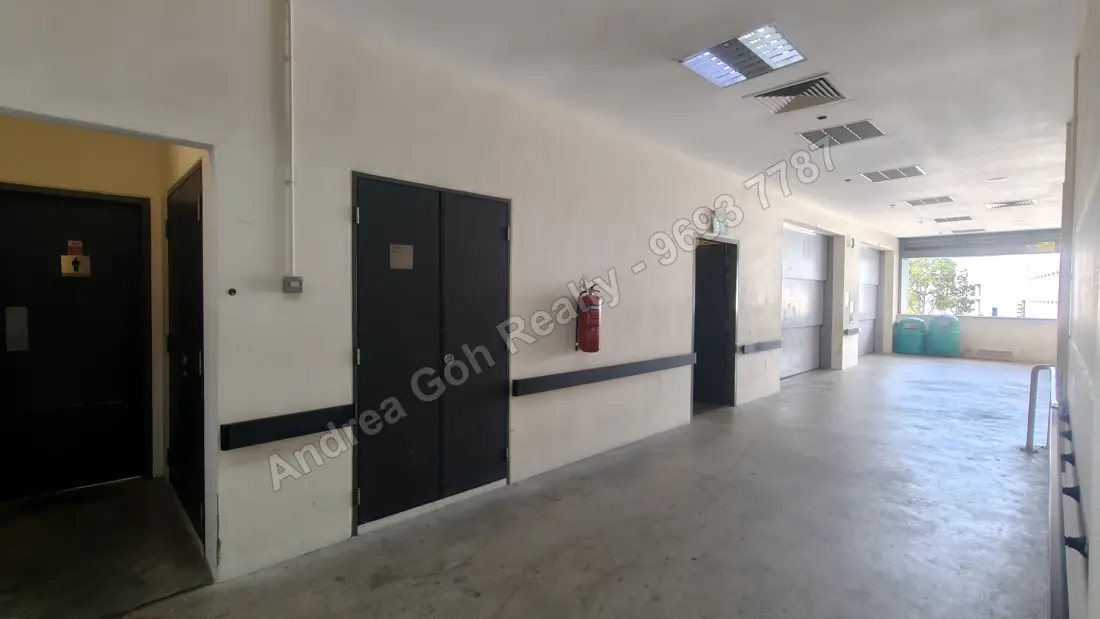
Inside the unit
Site photographs, 16 Apr 2026. Watermarked at build.
▶Full walkthrough
Unit interiorUnit interiorUnit interiorUnit interior
Specifications
Every detail, on the table
From the owner's fact sheet (24 Jul 2025) and URA SPACE; verify at viewing.
Units available
3 · 4,488 sqft total (corner pair combines to 3,089 sqft)
Running costs
MCST + sinking S$576 / S$475 / S$475 per month per unit (before GST); property tax S$4,590 / S$3,780 / S$3,780 per year
Power
60 amp, 3-phase
Parking
115 lots (97 basement, 18 outside); 1 season lot per unit at S$90/mo + GST, more subject to availability
Loading
6 x 40ft container/lorry bays with dock levellers; 2 scissor lifts
Lifts
2 passenger + 2 x 4,000 kg cargo lifts
Floor-to-ceiling
about 4.8 mⓥ
Floor loading
12.5 kN/m²
Land / GFA
6,327 m² land · 15,819 m² GFA · plot ratio 2.5
Why the address
Why the address
Google Places ratings and distances, indicative. Chosen for a working site — where staff eat, park and get supplies. The residential catchment is the whole Geylang planning area, not a walk-in radius; it is shown because several alternative uses here are assessable rather than barred, and a childcare operator in particular would underwrite against that household base.
Getting here
Macpherson MRT (Downtown + Circle Lines)↗5 min walk
OneMap-routed distances/times; ratings via Google Places, indicative and subject to change.
Getting there
MRT, bus and commute times
~5min walk
🚇 Macpherson
🚌 Bus stops nearby:
Opp Orion @ Paya Lebar111m
Paya Lebar Rd
82224284370768015843e70M
Opp Traffic Police125m
Ubi Ave 3
5858A
Le Crescendo139m
Paya Lebar Rd
8222428435870768015843e58B70M
Traffic Police153m
Ubi Ave 3
5858B
Paya Lebar🚇 11 min · 🚗 3 min (2 km)
SMU🚇 24 min · 🚗 13 min (7 km)
CBD (Raffles Place)🚇 27 min · 🚗 17 min (12 km)
SUTD🚇 33 min · 🚗 16 min (11 km)
one-north🚇 37 min · 🚗 24 min (19 km)
Changi Airport🚇 37 min · 🚗 21 min (15 km)
+6 more destinations
Orchard🚇 38 min · 🚗 16 min (10 km)
NUS🚇 39 min · 🚗 22 min (18 km)
Changi Business Park🚇 42 min · 🚗 17 min (12 km)
Mapletree Business City🚇 43 min · 🚗 25 min (17 km)
Jurong East🚇 50 min · 🚗 26 min (21 km)
NTU🚇 87 min · 🚗 34 min (28 km)
Times are indicative — weekday 08:30 for public transport (OneMap routing); drive times are off-peak, no live traffic — both vary with actual conditions.
Price evidence
Recent comparable sales
Actual caveats near the subject — verify on URA REALIS.
Street
Sold
Tenure
psf (strata floor area)
Paya Lebar 178 — this listing, standing stock
Advertised
Freehold
S$1,700
Paya Lebar 178 same floor run, 1,410 sqft (the fourth unit)
Jul 2026
Freehold
S$1,500
Paya Lebar 178 1,399 sqft
Oct 2025
Freehold
S$1,286
Paya Lebar 178 1,410 sqft
Feb 2025
Freehold
S$1,300
Paya Lebar 178 3,251 sqft
Jun 2024
Freehold
S$1,507
Generations @ Tannery ~1.3 km · TOP 2029 · sold out on launch day
Jul 2026
Freehold
L3 ≈ S$1,8xx
CT Gold, Lor Bakar Batu ~1.9 km · 63 units in two days
May 2026
Freehold
S$1,400–1,900
Same-building sales are URA caveats (via PropKaki, read 27 Oct 2026; verify on URA REALIS). The latest, Jul 2026 at S$1,500 psf, is the fourth unit in this same run; this listing asks S$1,700 psf, about 13% above it. Generations @ Tannery and CT Gold are NEW-BUILD launches of uncompleted buildings: they show demand for freehold B1 in this corridor, not the price of standing 2004 strata.
Corner pair, 3,089 sqftBSD ≈ S$201,763 on two contracts, ≈ S$232,164 on one · GST ≈ S$472,617
S$5,251,299
All three, 4,488 sqftS$1,700 psf, excl GST
S$7,629,599
Buyer's Stamp Duty, all three≈ S$290,277 on three contracts · ≈ S$351,079 on oneⓥ
≈ S$290,277–351,079
GST at 9%, all threefact sheet states price is subject to GSTⓥ
≈ S$686,664
MCST + sinking fundS$576 / S$475 / S$475 per unit, before GST
≈ S$1,526 / mo
Property taxS$4,590 / S$3,780 / S$3,780 per unitⓥ
≈ S$12,150 / yr
Indicative all-in + legal/valuation
≈ S$8.61–8.67M all three incl. GST and BSD (GST reclaimable if GST-registered)
Indicative only — confirm stamp duty, GST & apportionment with your lawyer / IRAS.
The abnormality
How rare is this, really?
Claim
Figure
Where it holds
Source
Private-sector multi-user factory space vacancy was 7.6% in 2Q 2026, down 0.4 points from 8.0% the quarter before (SingStat).
7.6%
island
SingStat, available and vacant commercial/industrial space (private sector) [1] · as at 2026-11-01
Multi-user factory rents rose 29.0% over the 5 years to 2Q 2026, against 25.6% for all industrial space (SingStat, JTC index).
29.0%
island
SingStat, Rental Index of Industrial Space (JTC) [1] · as at 2026-11-01
Multi-user factory prices rose 32.8% over the 5 years to 2Q 2026, against 26.9% for all industrial space (SingStat, JTC index).
32.8%
island
SingStat, Price Index of Industrial Space (JTC) [1] · as at 2026-11-01
Freehold industrial land sold at $727 (Feb 2023) and $841 (May 2025) psf ppr; JTC leasehold industrial land sold at $208 (May 2023) and $300 (Nov 2024). That is 2 and 2 sites in different places, so read it as a range, not a like-for-like pair. Freehold range: $727-$841 psf ppr.
$727-$841 psf ppr
island
Square Foot Research / EdgeProp government land sales, as at 2026-10-01 · as at 2026-10-01 (indicative)
New-sale industrial launches were priced at an average of $400 psf in 1995 and $726 psf in 2026 (+81.50%). This mainly reflects what each year's launches cost to build, land included, not growth in a unit you already own. Resale averaged $435 in 1995 and $595 in 2026 (+36.78%). 2026 is a part-year. The averages mix ages, locations and sizes.
81.50%
island
PropNex Investment Suite ProTrend, generated 30 Sep 2026 · as at 2026-09-30 (indicative)
New-sale industrial vs Resale industrial
How to read this. Each pair of bars compares the average price per square foot in 1995 (gold) with 2026 (green) for that type of property; the longer bar is the higher average. average $ psf, bars start at zero so lengths are in proportion. Same figures as the table above. 2026 is a part-year.
Figures are quoted or counted from the sources shown, at the narrowest scope they support -- never an unqualified 'only'.
The honest side
What could go against this?
JTC expects about 1.0 million sqm of new industrial space a year in 2027-2030, against average annual supply of 0.7 million sqm and demand of 0.6 million sqm over the past three years. (JTC Quarterly Market Report, 2Q 2026 [1], as at 2026-09-30)
Selling an industrial property within 3 years of buying it attracts Seller's Stamp Duty of 15%, 10% or 5% for a sale in year 1, 2 or 3 (IRAS), so plan to hold at least three years. (IRAS, Seller's Stamp Duty for industrial property (check current rates) [1], as at 2026-09-30)
Listed so you hear it from me first. Each point is a sourced fact, not a prediction.
A few questions worth asking
Here's the data. The conclusion is yours.
What did the market just do?
Two freehold B1 launches nearby sold out in under two days each
CT Gold took two days in Apr–May 2026; Generations @ Tannery, 1.3 km away, cleared all 59 units on launch day in July 2026 — and priced above CT Gold. Two data points, eleven weeks apart, same direction. Where does that leave standing freehold stock you can occupy now?
What does a lease cost you?
Freehold S$876 psf vs S$353 psf for 30-year leasehold
Q1 2026 averages (Savills). Freehold was the only tenure band to rise; 30-year leasehold fell. A shortening lease tightens financing and narrows the buyer pool at exit. What is not carrying that clock worth to you?
What are you not waiting for?
Built, occupied and available — not a 2029 completion
Buyers at Generations committed capital for roughly three years before they get keys. This floor exists, and the corner pair is available for occupation.
Sourced, past-tense market data. Not a forecast, an assurance of returns, or financial advice. Prices at record highs and volumes at a six-year low both hold at once — verify independently.
Why here
What is planned around this address
Published government plans near this property — the facts, with sources. What they mean for value is a question worth asking.
Can your staff get here without a car?
≈8,324 weekday arrivals alight within 400 m (10 bus stops · LTA passenger volume 202606)
Arrivals peak at 08:00 — a start-of-shift pattern, not a retail crowd. Staff you can recruit island-wide, and who can get to work without parking.
What is planned nearby (facts, not a forecast)
Thomson-East Coast Line (East) · Stages through 2026
New rail along the eastern corridor — Marine Parade, Marine Terrace, Siglap, Bayshore and Bedok South.
Source: LTA
Paya Lebar Central · Delivered; Airbase town from 2030s
URA's decentralised commercial hub on the Paya Lebar MRT interchange (East-West + Circle lines). Paya Lebar Quarter already delivers ~1m sqft of Grade-A offices (PLQ's ~10,000 office workers), a ~340,000 sqft mall with 300+ shops and 429 homes — a ~22,000-strong working catchment within a 7-min walk. Longer term, Paya Lebar Airbase relocates from the 2030s, freeing ~800ha for a new town of ~150,000 homes and lifting building-height limits across the east.
Source: URA Master Plan 2025; Lendlease (PLQ)
Sourced from URA / LTA / HDB plans — not a price forecast. Ask Andrea what it means for this address.
🏗️ New developments within 2km — the growth signal
JTC all-industrial price index sat at 114.9 in Q3 2026 (+1.0% QoQ, +4.2% YoY) (JTC via SingStat Table Builder).
JTC industrial rental index printed 114.4 in Q3 2026 (+2.1% YoY) — rents have risen for 24 straight quarters (JTC via SingStat Table Builder).
General market information on this page was last updated on 1 Nov 2026.
Straight talk
Objections, turned around
The real number, what it means here, and the question it leaves you with.
“Freehold industrial costs more psf than leasehold — why pay the premium?”
Q1 2026 average freehold industrial transacted at S$876 psf against S$569 for 60-year and S$353 for 30-year leasehold — freehold was the only tenure band that rose while 30-year fell.
What's a shortening lease worth giving up at financing and exit?
“Is a Change of Use to childcare or a canteen actually approved?”
URA lists childcare, an industrial canteen and general industrial use as assessable at this address — a Change of Use application it will consider, not a flat no; approval is never guaranteed.
Would you treat that as a plan, or as optionality on top of the industrial use you already have?
“Why S$1,700 psf when the fourth unit sold for S$1,500?”
The fourth unit in this run sold for S$1,500 psf in Jul 2026 (URA caveat); this asks about 13% more. Nearby freehold B1 launches priced S$1,400–1,900 psf, but those are uncompleted buildings.
What is a standing, available-now freehold unit worth to you against waiting for 2029?
"Why not just buy a residential property instead?"
A Singapore Citizen's 2nd residential property at this price pays S$475,659 in ABSD (IRAS rates as of 2026-10-21); this listing pays S$0.
Would you rather hand that to IRAS, or put it into the asset?
Straight answers
The questions buyers actually ask
Including the trade-offs — buy with eyes open.
What's the tenure and when was this built?
Freehold, TOP 2004, zoned B1 (light industrial).
How many units are available and what size?
3 units, 4,488 sqft total, priced from S$2,378,299 per unit — the corner unit and its adjoining neighbour combine into a single 3,089 sqft footprint.
What can I actually run here?
General industrial use as-is (4.8m ceilings, 12.5 kN/sqm floors, six dock-leveller bays, two 4,000kg cargo lifts). URA lists childcare, an industrial canteen and general industrial as assessable via a Change of Use application — approval is never guaranteed, so treat it as optionality, not a plan.
Is it tenanted, and can I get vacant possession?
To confirm with the seller's agent. Ask Andrea and she will check before you view.
Continue exploring
Also available
Not quite the one? A few more from the current collection in a similar bracket — happy to walk you through any of them.
Indicative for a non-residential resale purchase — GST timing and any ABSD depend on the specific unit; see the numbers section above. Confirm with your lawyer.
AG
Andrea Goh · PropNex Realty Pte Ltd (Licence No. L3008022J) · CEA R000289H
Priced and checked against official URA data — transacted comparables, stamp duty, and (where applicable) per-level approved use. No lead auction.